In 1981—the last year I was in college and the first year I was working at a real job, long-term interest rates got very high. I thought this was great. (I wasn’t in the market to take out a mortgage, but rather was starting to save money.)

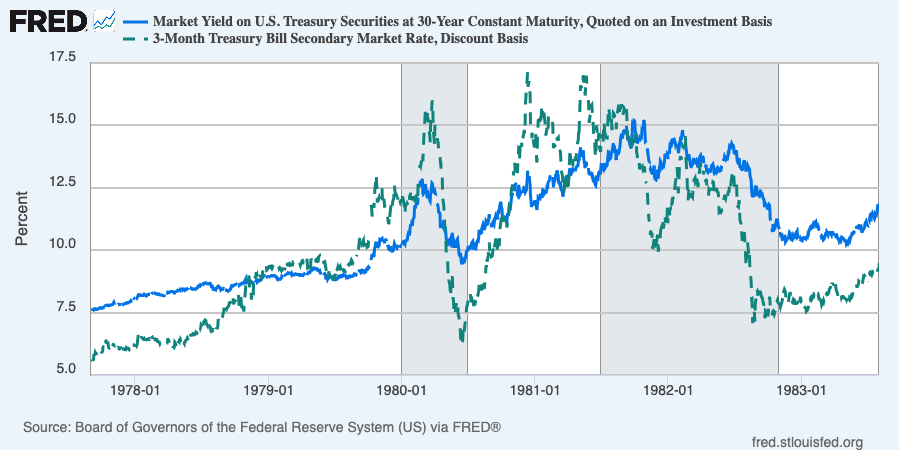
Graph of 3-month and 30-year interest rates from 1977 to 1983

I actually spent a lot of time calculating how much money I’d need to save and invest in long-term treasury bonds, in order to support myself without needing a regular job. I can remember when long rates got up around 14%, thinking that, since I could live on around $20,000 a year, I’d need a base amount of about $143,000 invested, plus enough extra to cover taxes, and to reinvest against inflation, totaling perhaps $300,000.

I was ahead of FIRE (Financial Independence Retire Early), and I rather missed out on the “reduce spending” half of the idea, so I didn’t make much progress toward my $300,000 goal for the first several years. It wouldn’t be until the early 1990s that I figured that part out, and by then interest rates were a lot lower. Worse, they were falling pretty fast, making the whole thing a lot harder.

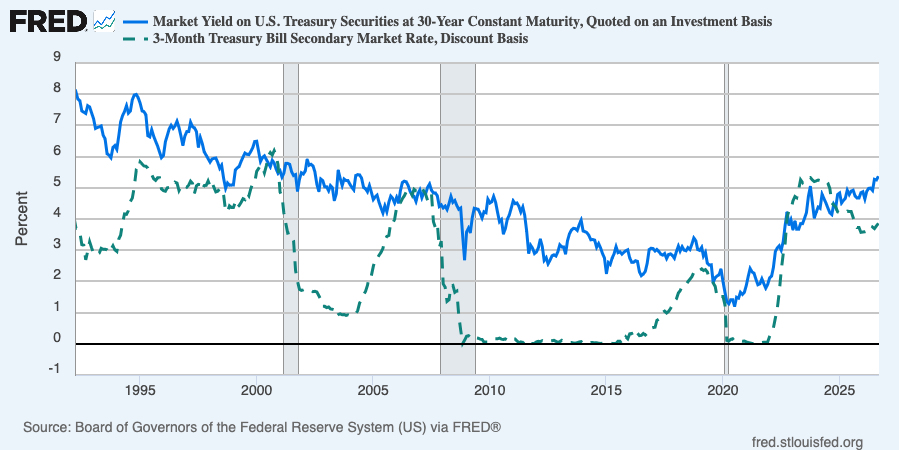
Graph of 3-month and 30-year treasury interest rates from 1992 to 2026

Rates kept moving against my goals pretty steadily, right through the great financial crisis in 2007, and then again during and after the pandemic in 2020. Of course inflation was falling until after the pandemic, making it seem a bit less difficult to invest enough that the return would support me even after allowing for inflation. (And, as a bonus, the Treasury started issuing TIPS, which adjusted their value to keep even with inflation, and paid their interest rate on the adjusted value. You still had to invest enough to cover inflation, but a lot of the risk and guess-work was removed.)

Now, finally, rates are moving in the right direction again. The 30-year TIPS is now paying an inflation-adjusted 3%.

The inflation calculator at the BLS says that $20,000 in 1982 is equivalent to $71,046 today. At 3% you’d need to invest $2,368,186 in TIPS to bring in that much cash. (But you wouldn’t have to worry about inflation.) Weirdly, the same BLS calculator says that the 1982 equivalent would have been $666,666. So just over double the $300,000 that I imagined would have sufficed back in the day. Which is perfectly reasonable, considering that back in the day I could have gotten 14% on my money.

Anyway, after a long period during which it was impossible to invest for a real return on a safe asset—what you want to do, if you’re doing the FIRE thing—we are finally back to having that option. It’ll be good for people like me. I think it’s good for the economy as well, even if it sucks if you want to take out a big mortgage so you can afford to buy a bigger house than you need.

A slug crawling on a wet sidewalk

I am almost completely unconcerned about the “dangers” of AI that I’m hearing about.

In particular, I’m completely unconcerned about the danger that terrorists (or bored high school students) are going to use AI to make a bioweapon. I guess the concern is that AI will be able to try thousands of changes in the time a human could try three? That is different from what evolution has been doing for two billion years in no way whatsoever.

Similar only in that it is another AI danger that’s easily ameliorated, is AI-facilitated hacking, which the AI firms want us to come up with regulations for.

The fact is, we scarcely need any new regulations at all. Just an ordinary legal structure where, if someone using AI does something improper, the legal and criminal liability falls equally on the person prompting the AI and on the company that wrote the AI.

Of course, if the harm passes through someone else who’s supposed to be taking due care (such as your bank or broker) that person also has ordinary responsibility. (So if an AI helps someone steal your retirement account, the broker holding your retirement account has to make you whole, just as if they had handed your money over to someone who hadn’t used AI. About the only AI-related regulation needed is something making it clear that the broker can not only sue the criminal who stole it, but also the AI firm whose tool was used to effectuate the crime.)

My point is that all those supposed horrible dangers are perfectly ordinary, and there is no need to do anything special at all.

What’s really interesting is why are the AI firms and AI scientists trying to gin up all this worry? Could it be that they can see that without some buy-in from governments the companies are all going to collapse in short order?

That’s my best guess.

The Bureau of Engraving and Printing has a bunch of downloadable guides to tell cashiers and tellers (and ordinary folks) how to identify genuine currency.

A $100 bill

So now seems like a good time to mention that a couple of new U.S. currency note designs came out while I was writing for Wise Bread, and each time I wrote a post or two about them:

And, of course, I wrote a general article on spotting counterfeits.

Many Americans want fewer immigrants, primarily because they worry that immigrants are competing with native-born U.S. citizens for jobs. There are of course other reasons. Some people are racists. Some people imagine that immigrant populations will include radicals or terrorists. But I think the jobs one is the big one.

Border fence with barbed wire at the top and a sign warning "Danger high voltage no trespassing"

I think I see a good way to fix this particular problem. A good enough way that we probably don’t even need to have visas, or immigration checks at the borders. Most important, we wouldn’t need to have a police state with ICE agents sweeping up brown people and demanding to see their papers.

My idea is simple: add a tax surcharge—perhaps 15%—on companies, on the payrolls of immigrants, legal or not. (Plus a twist I’ll mention in a minute.)

This fixes several problems at once.

First, it means people can quit arguing about whether companies are hiring immigrants because of their skills, or just because they’re cheaper or more willing to work long hours, or whatever. If companies are willing to pay an extra 15%, they’re definitely in need of the skills. (Maybe the ideal rate is 10% or 20%. It should specifically be enough that companies will hire native-born workers if they’re capable of doing the job, because they’re cheaper than foreign-born workers after taxes. A bit of experience will show us the ideal rate.)

Second, it’ll raise wages and salaries for Americans, because even a big raise would be cheaper than hiring an immigrant.

Third, it’ll greatly reduce the cost and trouble of the numerous visa programs. In fact, we can probably just get rid of visas. Anyone can come to the U.S. and work, as long as their employer pays the surcharge.

Of course this only works if employers actually pay the surcharge—and why would they do that, if they’ve been cheating on employing illegal immigrants all along?

Well, the twist I mentioned above is to solve that: Make the statute of limitations on this tax ridiculously long. Maybe 35 years. Add on some severe penalties for non-payment as well—double the original bill, plus interest and the ordinary penalties for unpaid taxes.

Oh, and spread the liability around. If the immigrant is technically employed by a contractor, but he or she works at your site, you’re also liable for the surcharge. (I don’t expect it would be possible, but I’d like to see the CEO be personally liable for the surcharge, in cases where the corporation went bankrupt somewhere along the line.)

With a policy like this in place, employers—instead of looking the other way when they suspect someone is an illegal immigrant—now really want to know. Because they either have to pay the surtax now, or else they’re on the hook for double that money for years into the future.

I’m thinking of 35 years, because it’s long enough that the immigrants might be reaching retirement age about then. If we throw in a little incentive—perhaps 10% of the tax collected—they might be willing to report all their former employers when they’re ready to retire. Remember: They don’t owe any extra tax—the liability is all on their employers. But they can collect that little 10% as a boost to their retirement by ratting out three decades of tax-cheating employers.

I think this solves everything.

Since everyone is legal, there’s no need to worry about whether someone is “documented” or not. No need to worry about visas. No need to check anyone’s papers.

Oh, there’ll still be a need for papers—employers will want to be sure a potential employee is a citizen—there’s just no need for the police to check them. And of course, some citizens might have trouble coming up with papers. But those problems are no worse than they are already, with the bonus that they can be sorted out at leisure in ordinary courts, rather than in special immigration courts with people in detention. Citizens can show they’re native born all sorts of ways, just like they do now if they need to get a passport, but don’t have a birth certificate. Naturalized citizens have naturalization papers, plus there are other records.

Companies can copy and maintain the documentation to show that their employees were citizens, or else pay the taxes.

Nobody is “illegal.” Anybody can call the police, get a drivers license, get car insurance, send their kids to public school, go to the doctor, all without any worry that they’ll be deported. (Of course, they might not stay long, if they don’t have skills that justify their employer paying an extra 15% tax to employ them, but that’s okay too.)

We can save a bunch of money on border security, because anybody can come into the country, as long as they’re willing to compete with the locals at a 15% disadvantage.

My main interest here is in getting rid of the need for police-state behaviors on the part of the government. If everybody is legal, there’s no need for them. My secondary interest is in living in a more diverse community. I like having foreigners around. I like living among a diverse ethnic population. I think it could be awesome.

As a bonus, those extra taxes will fund quite a bit of extra government spending. Maybe even makes some headway on the national debt.

I had completely forgotten about this post, written more than 20 years ago, even though I went on to write about exactly this topic for Wise Bread for years.

This post was about the difference between playing at being poor (which gives you a bunch of psychic benefits) versus actually being poor:

Playing at being poor means living in a cheap apartment, eating cheap, healthy food prepared at home, having only one car (and not a new one), and so on. It’s really only a matter of giving up stuff–and not even all stuff. You can easily justify an extravagance or two. You might give up cable, but have a cable modem. Give up movies, but go to plays. Give up coffee shop coffee, but buy Jamaican Blue Mountain for home. In many ways, it’s the way I live now. But I try not to be smug about it. I know the difference between what I’m doing and being poor.

Being poor isn’t frugal or safe or healthy. Being poor means skipping an oil change because the alternative is skipping lunch for ten days. Being poor means living in a dangerous neighborhood. Being poor means wearing shoes that hurt your feet.

The difference is a matter of capital. Having capital is frugal. If you have capital you can play at being poor and actually live more cheaply than a real poor person. A frugal person’s car lasts a lot longer than a poor person’s. You can buy when things are cheap, instead of paying whatever price they happen to be when you simply can’t do without them any longer. Similarly, it’s safer and healthier.

Source: 2002-03-06

There’s a bit more if you click through.

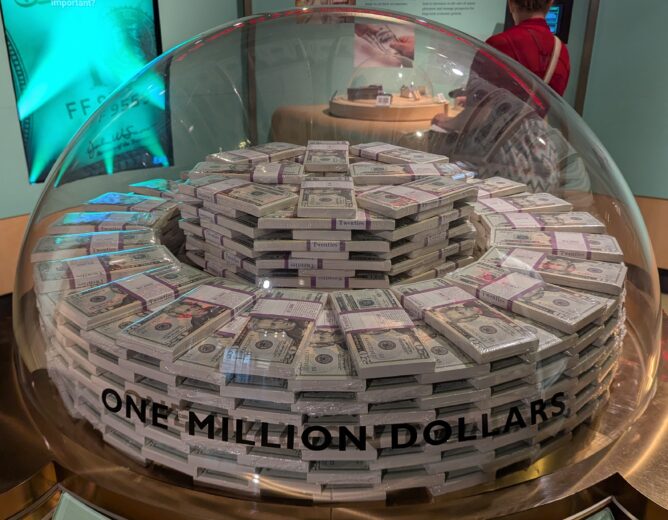
Museum exhibit at the Chicago Fed of $1 million in $20 bills

I’ve been warning about the current stagflation since the beginning of last year. It’s good to see others are catching up.

Stagflation, the Scourge of the 1970s, Is Back by Phillip Braun

One point the opinion piece makes is that the one bright spot in the economy—the stock market—is actually (in line with what I’ve been saying about how the markets and the business news have this all completely wrong) a “severe systemic risk.”

Sculpture of an allegorical figure of Industry, standing outside the Chicago Board of Trade

Some years ago, I wrote an article on living off capital and published it as a guest post on another financial blog. The old link to it is dead, and a google search doesn’t turn it up any more, so I thought I’d go ahead and repost it, hosted here on my own blog.

People who come from wealthy families learn how to live off capital. The rules are taught along with all the other things they learn from their parents—how to dress, how to eat, how deal with bankers and trust officers. But even though most people don’t learn the rules, living off capital is just a skill, and it’s one that everybody should learn, because everybody lives off capital sometimes.

People usually think about living off capital in the context of retirement, but that’s just one (albeit important) example. Perfectly ordinary transitions, such as losing a job and having to find another, also amount to living off capital. There is also the broad swath in between: Living off capital for longer than just the length of time it takes you to run through your emergency fund, and doing so without the institutional support—social security, medicare, maybe even a pension—that comes along with retiring at an ordinary retirement age.

Income

If you’ve got a lot of capital—that is, if you’re wealthy—then living off capital is easy: You invest enough in treasury bonds that you can live off the interest.

It’s not trivially easy, of course. You have to allow for taxes. You have to allow for inflation. You have to have some sort of cushion or reserve in case your investment return falls. But, generally, living off your income is straightforward.

You allow for taxes by setting aside enough of your income to pay your taxes. This isn’t hard, even if you have to file quarterly estimated taxes, but you have to do it yourself; you don’t have an employer automatically taking care of it for you by deducting it from your pay. Screwing up is expensive—screwing up badly may even be criminal.

You allow for inflation by reinvesting enough of your income to preserve the value of your capital. If your money is in US dollars, TIPS (Treasury Inflation-Protected Securities) will do exactly that. The principle value of the bonds increases automatically to keep you even with inflation, and the interest is paid out on the inflation-adjusted principle, so your income rises with inflation as well.

(The adjustment is based on the Consumer Price Index while what matters to you is your own cost of living, so you can’t entirely delegate the job of allowing for inflation, but TIPS will do most of the heavy lifting.)

You allow for reversals by having a cushion somewhere. Ideally, have two cushions: First, a reserve fund with enough money to cover any unexpected expenses. Second, some flexibility in your cost of living, so that a decline in income can be matched with a decline in spending.

Beyond just income

The wealthy have other concerns than just supporting themselves—they want to pass down an estate. Because of that, they teach their kids this rather conservative version of living off capital. If you only spend your income, and if you reinvest enough to keep even with inflation, then you’re preserving your capital intact. (If you reinvest more then the minimum, or if some of your capital is invested for growth, than you can be growing your capital at the same time you’re living off it.)

If leaving an estate is not a concern for you, then you can spend more than just your income.

There’s a common rule of thumb that (if you have a well-diversified growth portfolio), you can probably spend about 4% of your capital and still expect to have more capital the next year. That won’t be true every year (it was really, really not true in 2008, for example), but historically it’s been true on average.

Still, the wealthy know that spending capital is a bad idea. Anytime you spend more than your income, you’re in danger of entering a death spiral: Your reduced capital earns less money so you have to spend even more capital to support your standard of living; repeat until broke.

A lot of people have back-tested versions the 4% rule, looking at historical periods to see if following that rule ever led to a death spiral. From what I’ve seen, it looks pretty good, but the current circumstance is going to put it to a particularly harsh test–especially for people who started living off their capital in 2007.

If you can afford it, choosing to spend only income is a safer strategy. If you can’t, you probably ought to accept that at some point you’ll have to earn some more money—and if you’re going to do that, sooner is probably better than later (before you’ve depleted your capital). Happily, a pretty small amount of money can make a big difference, if you’re right on the edge of being able to live on capital. Every dollar you earn is a dollar of capital that can go unspent.

Investments

If you were really rich, the safest thing to do would be to invest enough in TIPS that the income would support you. Then you could invest the rest of your money however you liked. Most people aren’t that rich—at the moment you’d need close to $2.5 million invested in TIPS to earn an inflation-protected $50,000 a year. Treasurys without inflation protection are earning more than twice as much. (Of course, you have to reinvest a big chunk of that to keep even with inflation).

Dividend-paying stocks can earn still more money, and dividend growth can provide some amount of inflation protection (as can capital gains). in recent years it has been tough to invest for dividend yield, but even with the recent recovery in the stock market, there are plenty of companies paying a reasonable dividend now—there are more than 40 companies in the S&P 500 whose dividend yield exceeds the yield on a 30-year treasury. None of those will be as safe as treasurys, but at least there are some options now for someone looking for income.

If you have it in you to be a landlord, there’s also the option of earning rent on real estate investments.

Mechanics

You can arrange the mechanics several different ways. The simplest version is simply to have the income from your investments directed into your checking account and use it to pay your bills. A slightly more complicated version would direct your income into the savings account where you keep your reserve fund, and then transfer money from there into your checking account. That makes it easier to even out the month-to-month money flows, which tends to be necessary because stocks generally pay dividends quarterly and bonds generally pay interest semiannually.

(If a lot of your capital is tax-sheltered in an IRA, 401(k), or similar vehicle, the tax rules make it more complex to use that capital for spending, but there are rules for handling the case when you’re actually retiring early.)

The key step–the one that rich families make sure that their children know—is to evaluate your capital every year: Make a new budget with your projected expenses for the following year, and then reinvest enough of your surplus that its earnings will cover any increase in your cost of living.

If you don’t have enough of a surplus to do so, you were living beyond your means.

It’s easy to do this by mistake. Even most people with a budget don’t know their cost of living accurately enough to know if they’re properly accounting for things like those large-but-rare expenses like a new car or a new roof, and any particular category of expense can rise much faster than overall inflation. (Think health insurance, college tuition, and fuel.)

People who are accumulating capital (rather than living on it) can use each year’s new savings as a buffer—even a major un-budgeted expense can often be covered out of this year’s planned savings without needing to dip into capital. Someone already living off capital doesn’t have this option. They have to provide their own buffer out of their reserve.

Fluctuations in income

There’s a second reason that a reserve is essential: The income earned by capital fluctuates. Anyone living off capital right now knows this quite acutely—the rate paid on Treasury securities is at generational lows. Other investments (such as dividend-paying stocks) earn an income that doesn’t necessarily shift in lock-step with treasurys, but can still go down—particularly during a recession.

The children of rich families learn that the key technique for stabilizing your earnings from capital is diversification.

You should diversify across time by investing some of your money in long-term treasurys, which will pay a fixed rate for a long period (decades). That offers some stability, but has two downsides. First, it while it protects you from falling rates, it makes it harder to take advantage of rising rates. Second, if all your treasurys mature at once, you might have to reinvest the whole sum at a much lower return. Avoid that making sure that your long-term securities mature in a staggered fashion. (Arranging for a fraction of your long-term securities to mature at regular intervals is called setting up a ladder.)

You should also diversify across kinds of investments by investing in more than one kind of vehicle. As attractive as TIPS are for someone living off capital, you probably want to have some of your money invested in ordinary treasurys, in stocks, and maybe in real estate. Other options (such as owning a business) are worth considering as well. This reduces the chance that your income streams will all fluctuate in the downward direction at the same time.

Other kinds of diversity are good as well. Consider investing in foreign treasurys as well as US issues, and maybe in corporate or municipal bonds.. Your stock investments should include multiple companies in different industries, and should include foreign companies as well as domestic ones.

The other key for dealing with a fluctuating income is to have a flexible cost structure, so that you have the option to cut your expenses, if necessary, to match your diminished income.

Those are the basics:

  • Invest for income
  • Reinvest to preserve your capital
  • Diversify
  • Keep enough flexibility that you can adjust your expenses

Learn those skills and you’ll have as much ability to live off capital as someone who grew up in a wealthy family. Then you just need the wealth.
If, like me, you had any sort of reasonably balanced portfolio at the beginning of the year (or the beginning of last year), it’s worth observing that it is almost certainly way, way out of balance.

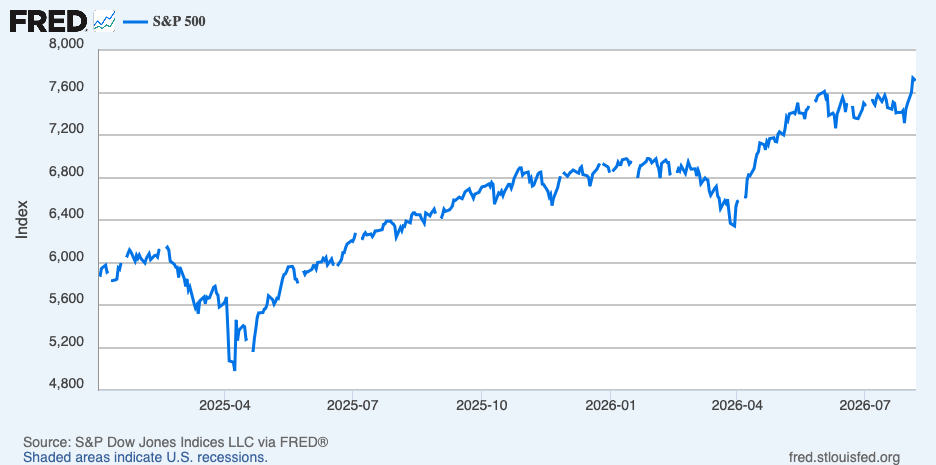
Graph of the S&P 500 since January 1 last year, showing an increase from under 6000 to over 7600

If so, this is your reminder to rebalance your portfolio.

Doing so is admittedly really hard to do. If you had a 60:40 (stocks to bonds) portfolio at the beginning of last year, you might very well have 70% or 80% invested in stocks now, and that probably feels great. You feel like a genius, letting your profits run. If there’s anything better than having 60% of your portfolio grow at 20% a year it’s having 80% of your portfolio grow at 20% a year.

But you know it’s a terrible idea. It’s bad enough to have 60% of your portfolio lose half its value. Having 80% of your portfolio lose half its value is much, much worse.

Knowing that it’s hard, let me point out a little thing that might make it a little easier right now: Bond rates are up nicely. You can get nearly 5.25% on 30-year bonds, or almost 3% on inflation-adjusted bonds. That’s good enough that you don’t really need to agonize about whether you can expect a capital gain or capital loss on the bond. Just buy it and take the coupon.

Of course, I have no idea what balance is right for your portfolio. Maybe it’s 60:40. If you’re young, maybe it’s 80:20. If you’re retired, maybe it’s 35:65. But if you had a sensible balance a year or two ago, and you haven’t rebalanced, it is now way out of whack.

This is your reminder to fix that.

AI firms are on the ropes, having spent way too much money building infrastructure for tools that are valuable, but not nearly valuable enough to support the money already spent, let alone what they’re planning to spend over the next two or thee years. This is bound to come to a bad end.

As Jerry Holkins puts it:

They can only loan each other money for so long. Then, they’ll socialize the losses through nationalization.

Source: Cyberbullies – Penny Arcade

At least, that’s their plan. Oliver Jutel and Gil Duran have a name for this plan: “exit through the state.”

Because I’m at heart an optimist, I like to imagine a more hopeful solution—one where this plan fails. And I legit think it might.

If Congress changes hands, and Trump becomes even more toxic (two things that seem very likely), there might not be anybody in a position to lead the charge for socializing the losses. A toxic Trump trying to hand another bunch of taxpayer money over to billionaire tech bros might actually be very unpopular. And if a Republican minority in Congress can’t get it together to come up with a plan that a significant number of Democrats will support, socializing the losses just might not happen.

But it has to “not happen” right then—with a Democratic (or divided) Congress.

If the AI firms can hold things together (with circular financing, SPVs, and the like) until there’s a Democrat in the White House, that guy will probably not be able to resist the pressure to “do something.”

If—as I hope, and kind of expect—it comes to a head before that, the Republicans might well not be able to come up with a plan that meets the demands of all their different constituencies, while the Democrats refuse to join in any plan that a large subset of Republicans will agree to. The result might just be that we just let the sucker go down.

Letting the sucker go down is what George W. Bush wouldn’t do in 2008. Except, of course, he kinda did, as far as homeowners were concerned. Banks, investment firms, and insurance companies got saved. Homeowners got hung out to dry.

My point being that the government is totally willing to let some suckers go down. The Republicans would like those suckers to be ordinary investors, computer users, and (in particular) tax payers. But I like to imagine that there’s at least some chance that the politicians will simply be unable to cobble together an arrangement to accomplish that, with the result that the AI firms go down, a bunch of AI firm executives get prosecuted for investment fraud, and all that infrastructure (data centers and large language models) gets sold off in bankruptcy, ending up in the hands of people with a certain amount of rationality (and much less debt).

A graph of oil prices, showing the peak during the war, and the start of another peak now

A few weeks ago, back before the Iran war heated back up, The Economist wrote a mia culpa, explaining why they’d gotten it wrong about the war being an economic disaster. Briefly, while the MOU was holding up, I was tempted to write my own.

Like The Economist editors, I had thought back in April that Things are amazingly more bad than markets seem to think, but by the beginning of June, it was looking like maybe the risk of catastrophe had eased.

I didn’t write a mia culpa. To be fair, part of that was just laziness. But part of it was looking at things and thinking I was still right. Maybe between some demand destruction and some dribs and drabs of oil getting through the strait, world markets had found a new equilibrium that wasn’t nearly as bad as I’d expected. But I didn’t think so.

The Economist thought so. They thought they’d gotten it wrong for two reasons:

First, we thought that America and Iran would hold out against a deal to reopen the Strait of Hormuz: America because Mr Trump deludedly thought he held the whip hand, Iran because its regime knew its people could be made to endure more pain. In fact, facing the fury of American motorists, Mr Trump all but folded, preventing a disaster. Since the two parties struck a provisional deal in June, enough oil has been getting out of the Gulf to reassure markets that supply is coming back online, even if the future of the strait remains uncertain.

Our second oversight was, like others, not anticipating the staggering degree to which China would be able to slash its oil imports. Crude imports are 5m barrels a day lower than a year ago, despite the fall in prices. China has cut its demand and shored up supply. Its oil reserves are opaque—many barrels are hidden from satellites underground, and there is a blurred line between official reserves and corporate inventories. But they have been shown to be a powerful buffer.

I pretty much bought their second point. China had produced a truly fantastic amount of demand destruction, and had done it with minimal impact on their own economy, by largely shifting the impact onto people in other countries who had bought their oil distillates, before China prohibited exports. They could probably keep that up indefinitely, removing their demand from the world market.

That first point, though, I found doubtful. I mean, yes, Trump always chickens out, which is why we got the MOU and the briefly partially reopened strait. But I think they were wrong in thinking that Iran would go along with what Trump wanted, or that Trump could settle for what Iran would (obviously) want to do. They tried to paper over the cracks for a few weeks. I mean, I believe Trump settling for whatever Iran did and pretending it was a victory was a thing that could happen. But I’m not surprised it didn’t work out. Too many other people in the U.S. government were simply unwilling to let Trump leave the strait in Iran’s hands. And, although oil prices were coming back down, they were not on a trajectory that would improve the Republican’s chances in the midterms.

So, I think The Economist was right in the first place, and wrong to imagine that Trump and Iran could agree that “preventing a disaster” was something they could do.

The oil price graphic above is already out of date. It shows yesterday’s closing price, and things have gotten worse already today. Brent crude is over $100 as I wrap up this post.